

Everyone talks about China as a world leader in scaling technology. But the real point is not simply that China can manufacture cheaply. The real point is that China has learned how to turn “not yet perfect” technology into mass-market industries before the West even agrees that the category is real.
DJI is the classic example. Before DJI, drones were expensive, unstable, specialist products. Then DJI made drones good enough, affordable enough, and easy enough for ordinary users and professionals. That created the market. Today DJI is estimated to hold around 70% of the global drone market, and even more in some consumer and commercial categories. (SCSP)
Unitree may now be doing something similar with humanoid robots. Many Western observers still dismiss the robots as dancing machines, toys, research platforms, or entertainment robots. That may be the mistake. The same happened with DJI. The first products do not need to be perfect. They need to be good enough to create demand, generate revenue, collect data, improve components, and fund the next generation. The Unitree discussion makes exactly this point: iteration speed matters more than the demo, and the DJI/BYD playbook is about moving fast through imperfect but increasingly useful products.
Unitree is no longer just a small robotics curiosity. It has received approval for a Shanghai STAR Market IPO and plans to raise about 4.2 billion yuan, or around $619 million, to invest in robot AI models, new robot bodies, product development, and a smart robot manufacturing base. (Reuters) Reuters also reported that Unitree’s operating income grew 335% year-on-year in 2025, humanoids became its main growth driver, and the company shipped more than 5,500 humanoid units last year. (Reuters)
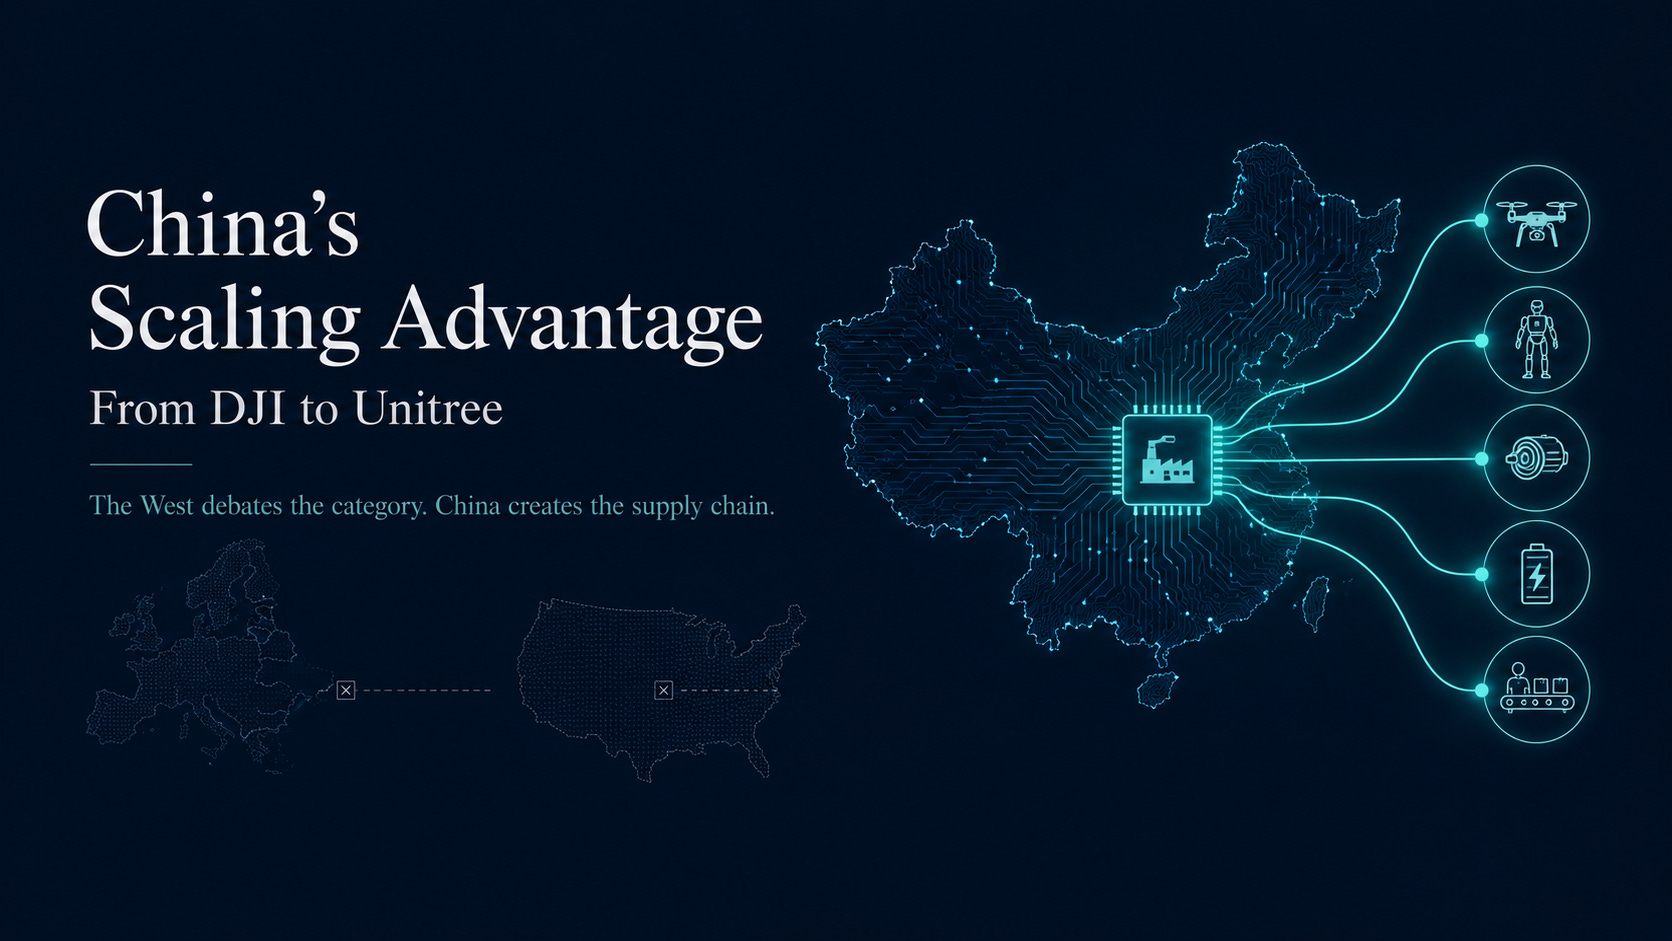
This is where China’s advantage becomes visible. The West often wants the perfect product first. China often builds the imperfect product, sells it, improves it, and scales it. The West debates the category. China creates the supply chain.
The reason this matters especially for humanoids is that robotics is not just software. You cannot simply “AI your way out” of a hardware problem. A humanoid robot is motors, actuators, batteries, sensors, thermal management, gears, materials, electronics, factory process, quality control, service, and cost reduction. Experts say that actuators can represent 50–70% of the bill of materials. If you cannot make those cheaply and at scale, your robot may be smarter — but it will still be too expensive.
Europe and the US still have enormous strengths: research, software, design, premium engineering, capital, brands, universities, and high-end industrial know-how. But they often struggle to scale new physical technologies because the ecosystem is fragmented. The US is strong in software and venture capital, but weaker in dense manufacturing supply chains. Europe is strong in precision industry, but slower in procurement, risk-taking, market creation, and pan-European scaling.
China’s edge is the full loop: ambitious entrepreneurs, dense supplier networks, fast component iteration, aggressive pricing, government support, local demand, and a willingness to scale before everything is perfect. That is why DJI won drones. That is why BYD surprised the car industry. And that is why Unitree should be taken seriously in humanoids.
The lesson is not that Europe or the US should copy China blindly. They cannot and should not. But they must understand the playbook.
The top 5 lessons
First, ship earlier. Do not wait for the perfect product. A “good enough” product can create the market, fund the next version, and start the learning flywheel.
Second, own the critical components. In drones it was flight control, cameras, batteries, motors and manufacturing. In humanoids it will be actuators, hands, batteries, sensors, robot bodies, data, and AI control systems.
Third, build supply-chain depth, not just startups. A robotics industry is not only Figure, Tesla, Apptronik or Unitree. It is also CNC shops, magnets, motors, gears, cables, PCBs, sensors, testing equipment, assembly workers, technicians, and tacit manufacturing knowledge.
Fourth, use real deployments as the laboratory. Entertainment robots, research robots, inspection robots and factory pilots may look small. But they create data, revenue, customer feedback, and engineering pressure. That is how products improve.
Fifth, create markets, not just regulations. Europe in particular must stop thinking that its main role is to regulate technologies invented and scaled elsewhere. Governments, large corporates, hospitals, logistics companies, infrastructure operators and manufacturers should become early customers of European technology.
The uncomfortable truth is this: China scales because it treats manufacturing as strategy. Europe often treats it as legacy. The US often treats it as something to outsource until it becomes geopolitically urgent.
Humanoid robots may be the next test. If Unitree becomes the DJI of humanoids, we should not pretend it came out of nowhere. The signals are already visible.
That is true in many cases, EV is a prime example. But to be fair, there are Figure AI and Agility Robotics. Both American and arguably one step ahead of Unitree in industrial deployment. (which is the key for unlocking humanoid potential).
Strong framing on China’s scaling advantage. The data in Unitree’s own filing made me separate two stages of the flywheel: 73.6% of humanoid revenue in the first nine months of 2025 was research and education, while defined manufacturing, inspection, and logistics uses were only about 2.6%. That does not negate the DJI/BYD playbook; it shows what the playbook is buying today—more experiments, not yet a mass labor market.
I wrote through that distinction here: https://tomfuture3labs.substack.com/p/unitree-has-the-byd-playbook-it-still. Curious whether you expect the application layer to consolidate around robot makers or independent embodied-AI vendors.